All Categories
Featured
Medicare Part D Enrollment and Drug Advice

Strategic Whole and Term Insurance Strategies
Security Plans Using Whole Life Insurance
Table of Contents
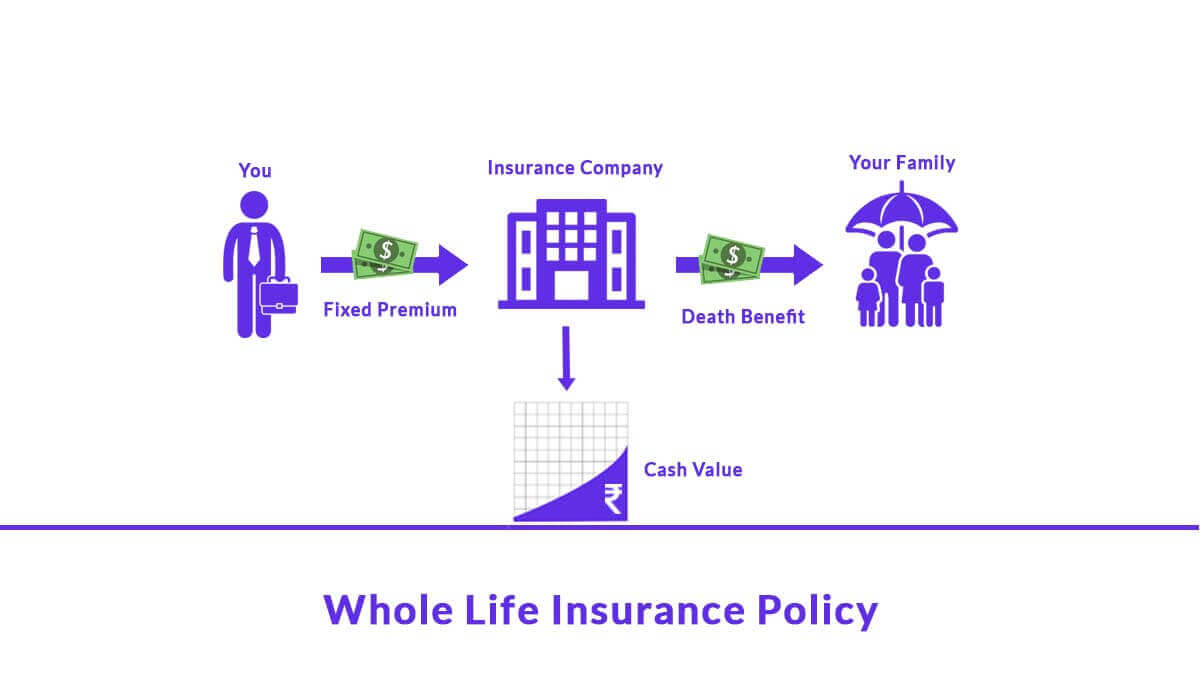
As quickly as the first premium is paid, the whole survivor benefit is set aside for your family. Income tax-free survivor benefit: The death benefit of a life insurance policy is not typically subject to federal earnings taxes. Tax-deferred development: The growth of cash worth within entire life insurance coverage is tax-deferred while the funds stay in the policy.
This suggests withdrawals to the degree of cost basis are thought about an earnings tax-free return of expense basis. Tax-favorable access to cash worth loans for any factor: During the insured's life, money value loans taken versus a whole life policy are ruled out to be a taxable event, even though the policy might have a big gain in excess of premiums paid.
Self-funding: The policy can pay for itself gradually by applying dividends to pay premiums, which adds to the policy's cost savings part. Special needs security: An entire life policy can continue to be moneyed even if you are handicapped. When you choose the Waiver of Premium rider9, if you suffer a qualifying special needs, your policy will continue to provide death advantage defense, have cash value growth, and pay dividends even while you aren't paying premiums.
10Distribution: If properly performed, life insurance assists prevent probate and can provide beneficiaries with higher privacy than might be afforded by a will; a will ends up being public once probated, whereas death benefit circulations are typically personal, contractually driven transactions. As soon as a policy loan has actually been taken, the yearly dividend can be utilized to assist repay the policy loan.
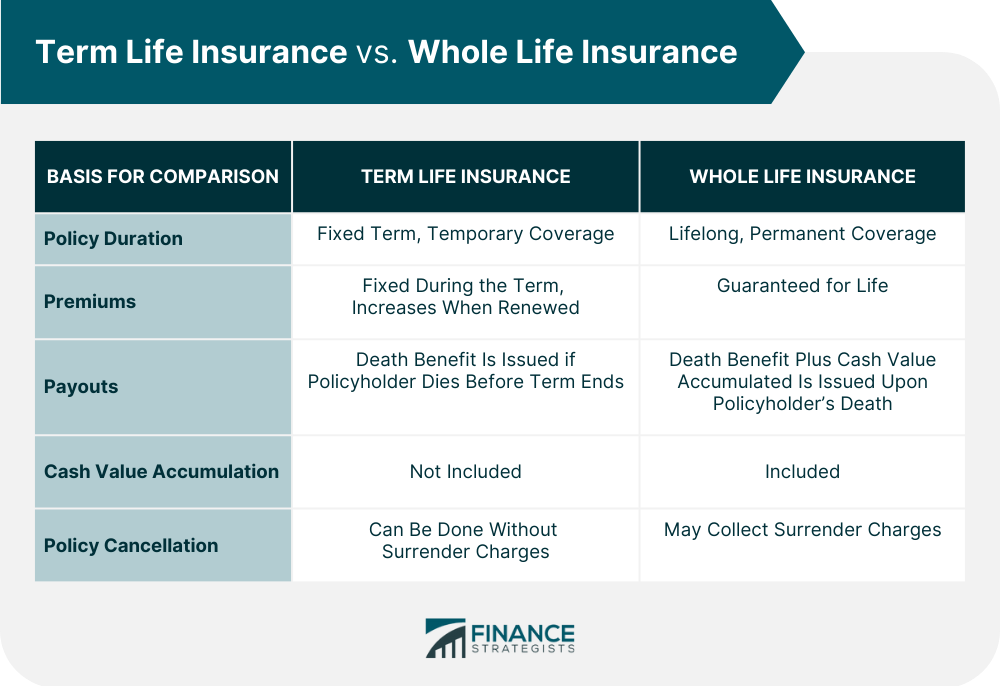
Functions, provisions, and costs vary from one insurer to the next, and each entire life agreement is unique to the insurance policy holder. Entire life insurance rates depend on elements such as age, health, and protection quantity, so it's essential to consider these when assessing policies. Normally speaking, there are two standard types of payment structures for entire life: Level premium entire life: This is the most common kind of whole life insurance.
Independent Insurance AgencyIndexed Universal Life Benefits for Long-Term Retirement
Minimal payment whole life: This kind of policy has a set level premium like a level premium whole life policy, however the premium is only payable for a set amount of time. The advantage is that they are ensured to be paid up at the end of the payment duration, so no payment is required at later ages.
Their schedule and expense depends on the policy and the insurer. In addition to the Waiver of Premium rider discussed above, some other choices offered by Guardian include: Paid-Up Additions Rider: The PUA rider can help increase the accumulation of tax-deferred cash worths and survivor benefit. The higher the premium paid into the rider, the higher the defense afforded by the policy.

It gives you a distinct chance for index-linked upside potential and the floor makes sure that your year-to-year disadvantage market direct exposure is restricted. Accidental Death Advantage: Supplies an additional death advantage if death takes place by unexpected bodily injury. Accelerated Advantage Rider: Offers accelerated benefits, allowing you to access a portion of the death advantage early if you are identified with a chronic or terminal health problem.
Final Expense and Burial Coverage for Seniors
Surefire Insurability Choice (GIO): Offers the policy owner the right to purchase extra insurance coverage without proof of insurability. The GIO can become much more valuable in the event of impairment: An insured who is disabled and has their premium waived may work out the GIO rider, and Guardian will pay the premium on the brand-new policy A whole life insurance coverage policy is one of the most important monetary purchases you can make.
12 Comparing life insurance companies and their life insurance coverage offerings such as entire life, universal life, fixed premiums, ensured death advantages, and cash value growth is necessary to finding the ideal policy for your needs. There are trustworthy, independent sources for monetary strength scores, such as A.M. Finest, Moody's, Standard & Poor's and Fitch.
Discuss your circumstance with an insurance expert or financial expert who understands entire life insurance coverage and can guide you to the option that finest meets your needs. If you do not know such a professional, ask a good friend or coworker for a suggestion. Or, Guardian can link you to a financial professional who can assist.
A whole life policy has money value that grows gradually. You can cash it out to assist supplement retirement, or borrow versus it at any time, for any factor. Entire life policies have a component referred to as the policy's cash worth: A portion of your premium dollars can grow over time on a tax-deferred basis, so you don't pay taxes on the gains.

Latest Posts
Comparing 2026 Term Life Insurance Rates for Families

Is Catastrophic Health Insurance a Good Deal for 2026?

Medicare Part D Enrollment and Drug Advice